by barefootins | Sep 4, 2026 | Florida Insurance, Personal Insurance
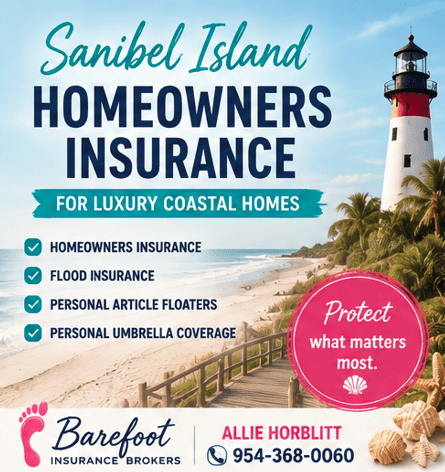
Finding Reliable Homeowners Insurance in Sanibel, Florida
Sanibel Island is famous for its natural beauty, wildlife refuges, and luxurious waterfront homes. Protecting these properties requires specialized Florida homeowners insurance designed for coastal environments and discussed with skilled insurance professionals.
Barefoot Insurance Brokers help residents across Sanibel Island compare multiple insurance options to secure competitive coverage at the right price. Barefoot Insurance Brokers represent many Florida based insurers to offer competitive options and great value to the local community.
Key Insurance Coverages for Sanibel Homes
Sanibel homeowners often consider combining several types of protection, including:
• Homeowners Insurance for wind and property coverage
• Flood Insurance for coastal flood zones
• Personal Article Floater policies for valuables
• Personal Umbrella policies for additional liability protection
Why Flood Insurance Matters on Sanibel
Many homes on Sanibel sit within FEMA flood zones, making flood insurance an essential protection for property owners.
Barefoot Insurance Brokers helps residents obtain both:
• National Flood Insurance Program policies
• Private flood insurance options with higher limits
Insurance Guidance from Allie Horblitt
Florida insurance broker Allie Horblitt works with homeowners throughout Sanibel Island to help them compare policies and understand coverage options.
Request a Free Insurance Review
Residents of Sanibel Island can contact Barefoot Insurance Brokers today.
About the Author
Alexandra “Allie” Horblitt is a Licensed Independent Insurance Agent with Barefoot Insurance Brokers., bringing over 14 years of industry experience to her clients. She specializes in marine artisan insurance, workers’ compensation including USL&H, general liability, and commercial auto coverage. Allie is licensed to sell commercial insurance products in Alabama, Florida, Georgia, Colorado, Indiana, Ohio, Texas and Virginia. To connect with Allie for customized coverage solutions, email her at allie@barefootins.com or call/text 786-440-8242
by barefootins | Aug 21, 2026 | Florida Insurance, Personal Insurance
Buying a home in Margate, FL means thinking about more than the purchase price and mortgage payment. Homeowners insurance can become an important part of both your closing process and your long-term cost of owning the property.
For buyers in ZIP code 33063 and surrounding Margate communities, Florida’s insurance market can feel complicated. Roof age, construction, wind mitigation features, prior claims, replacement cost and flood exposure can all affect the options available.
The good news is that you don’t have to figure it out alone.
Barefoot Insurance Brokers has been helping Florida consumers navigate the insurance marketplace since 2013, with a brick-and-mortar office right here in Margate, next door to the DMV on Banks Road.
Start Shopping for Insurance Before Closing
One of the easiest mistakes a Florida buyer can make is waiting until the last minute to obtain homeowners insurance.
Instead, begin the insurance conversation while you’re still working through inspections and financing.
An insurance agent may need information about:
- Year the home was built
- Roof age and roof covering
- Electrical system
- Plumbing
- HVAC system
- Construction type
- Wind mitigation features
- Prior claims
- Desired coverage
- Mortgage requirements
Older properties may also require inspection documentation such as a four-point inspection.
Starting early gives you more time to resolve questions before your closing date starts galloping toward you.
Market Value and Replacement Cost Aren’t the Same Thing
Your home’s purchase price isn’t necessarily the amount for which the dwelling should be insured.
Homeowners insurance generally considers the estimated cost to repair or rebuild the structure after a covered loss.
Land value is different from reconstruction cost.
That distinction is particularly important when real estate prices move up or down. A declining sale price doesn’t automatically mean a home should have a proportionally lower dwelling limit.
Why Wind Mitigation Matters in Broward County
Florida homes face significant wind exposure.
A wind mitigation inspection documents construction features that may help a home withstand hurricane-force winds.
Depending on the home, an inspection may document features involving:
- Roof shape
- Roof-to-wall connections
- Roof deck attachment
- Secondary water resistance
- Window and door protection
- Garage door protection
Qualifying mitigation features can affect the wind portion of a homeowners premium, which makes the wind mitigation report an important document when shopping for coverage.
Don’t Forget About Flood Insurance
Homeowners insurance and flood insurance solve different problems.
A standard homeowners policy generally doesn’t provide coverage for flooding caused by rising water.
Margate participates in the National Flood Insurance Program’s Community Rating System, and the City maintains flood-zone information and resources for residents.
Even when a lender doesn’t require flood insurance, buyers should still understand the property’s flood exposure and consider obtaining a quote.
Barefoot can compare available NFIP and private flood insurance options depending on the property and eligibility.
Questions to Ask Before You Buy
Before closing on a Margate home, consider asking:
- How old is the roof?
- Is there a current wind mitigation inspection?
- Is a four-point inspection required?
- Are the windows or shutters impact rated?
- Has the property had prior insurance claims?
- What flood zone is the property in?
- Does the lender require flood insurance?
- What is the estimated replacement cost?
- Are there features such as a pool, screened enclosure or detached structure that should be discussed?
- What deductibles are available?
These questions can uncover insurance considerations while you still have time to address them.
Why Shop More Than One Insurance Company?
Different insurers can have different underwriting guidelines, pricing, deductibles and eligibility requirements.
That’s one reason working with an independent insurance agency can be useful.
Barefoot Insurance Brokers represents multiple homeowners insurance markets and researches underwriting criteria to help match customers with appropriate available options.
Our homeowners markets include insurers such as Security First, Cypress Property & Casualty, Universal Property & Casualty, Monarch National, Edison, Florida Peninsula, Ovation, SageSure, Swyfft, Slide, Patriot Select, American Traditions, American Integrity, Orchid and other available markets.
Availability depends on the individual property and current underwriting requirements.
Local Help in Margate
Barefoot Insurance Brokers isn’t a national call center pretending to be local.
Our Margate office serves the community with knowledgeable insurance professionals who work in the Florida market every day.
We are an independent, woman-owned insurance agency established in 2013, and many of our customers have been with us since the agency’s early years.
Our goal is straightforward: research the available options, communicate clearly and make buying insurance as hassle-free as possible.
Frequently Asked Questions
Is homeowners insurance legally required in Florida?
Florida generally doesn’t require homeowners to purchase a homeowners policy simply because they own a home. Mortgage lenders, however, typically require borrowers to maintain acceptable property insurance.
Does homeowners insurance cover flooding?
Standard homeowners policies generally exclude flood damage caused by rising water. Flood insurance is normally purchased separately through the NFIP or an available private flood insurer.
Should I get a homeowners quote before making an offer?
You can begin researching insurance early, but a meaningful quote generally requires details about the specific property. Once you are seriously considering a home, obtaining insurance information before closing is wise.
Does a lower home purchase price mean I need less insurance?
Not necessarily. Market value and the estimated cost to rebuild a home are different measurements.
Can wind mitigation lower my insurance premium?
Qualifying wind-resistant construction features documented through an acceptable inspection may qualify for applicable mitigation credits.
Can Barefoot also quote my flood and auto insurance?
Yes. Reviewing home, flood and auto together can also help identify gaps, overlapping needs and available carrier opportunities.
Buying a Home in Margate?
Whether you’re moving across Broward County or relocating to Florida, Barefoot Insurance Brokers can help you research homeowners, flood, auto and umbrella insurance options before closing.
Visit or contact our Margate, Florida office to speak with a knowledgeable local insurance professional.
Coverage, discounts, underwriting requirements and eligibility vary by insurer and property. This article is general educational information and isn’t a substitute for reviewing the specific policy and property.
About the Author
Kassy Mendez is a Licensed Independent Insurance Agent with Barefoot Insurance Brokers, bringing years of industry experience in personal lines coverage to Florida homeowners and families. Her areas of expertise include flood insurance, homeowners insurance, high-valued and coastal home insurance, wind-only coverage, personal umbrella policies, and auto insurance throughout Florida. Kassandra Mendez is known for helping her insurance clients navigate complex risk exposures with clarity and confidence. You can reach Kassy Mendez directly at kassy@barefootins.com or call/text 754-233-0637 to discuss your insurance needs.
by barefootins | Aug 6, 2026 | Personal Insurance
Dog Liability Insurance in Brevard County | Barefoot Insurance Brokers
Brevard County dog life is laid-back, outdoorsy, and social. But beach walks, trails, and family neighborhoods also mean more interactions and more risk.
Under Florida’s new law, dog owners may now need liability insurance after an incident.
Why It’s Worth Having
Dog liability insurance helps with:
• Bite-related injuries
• Legal costs
• Claims not covered by renters or homeowners insurance
Great for:
• Young families in Viera
• Renters in West Melbourne
• Beachside living in Cocoa Beach
You can love the outdoors and still protect your future.
📞 Call/Text: 786-440-8242
📧 Email: allie@barefootins.com
About the Author
Alexandra “Allie” Horblitt is a Licensed Independent Insurance Agent with Barefoot Insurance Brokers., bringing over 14 years of industry experience to her clients. She specializes in marine artisan insurance, workers’ compensation including USL&H, general liability, and commercial auto coverage. Allie is licensed to sell commercial insurance products in Alabama, Florida, Georgia, Colorado, Indiana, Ohio, Texas and Virginia. To connect with Allie for customized coverage solutions, email her at allie@barefootins.com or call/text 786-440-8242
by barefootins | Jul 27, 2026 | Florida Insurance, Personal Insurance
Purchasing a luxury home in Florida is exciting, but insuring it requires more than selecting a standard homeowners policy.
Whether you own a waterfront estate in Palm Beach, a custom home in Parkland, or a high-rise condo overlooking the ocean in Sunny Isles Beach, your insurance needs can be very different from the average homeowner.
What Makes a Home High Value?
Many luxury homes include features such as:
Custom architecture
Premium roofing materials
Imported flooring
Outdoor kitchens
Wine rooms
Smart home systems
Detached guest homes
Pools and spas
Waterfront docks
And a TIV or Total Insured Value of $1 Million or more.
Replacing these features after a major loss can cost significantly more than standard construction.
Florida’s Coastal Risks
Luxury properties often face additional considerations, including:
Hurricane wind exposure
Flood risks
Higher rebuilding costs
Coastal construction requirements
Increased labor and material costs
Understanding how your Florida Home Insurance policy addresses these factors is essential before a claim ever occurs.
High-Rise Condo Owners Need Different Coverage
Condo owners in areas like Brickell, Aventura, and Sunny Isles Beach often assume the association covers everything.
In reality, owners may still need protection for interior improvements, personal belongings, liability, and certain assessments charged by the association.
Reviewing Coverage Before You Need It
Every property is different.
Reviewing your insurance before hurricane season, after renovations, or when purchasing a new home can help identify potential gaps and ensure your coverage reflects your property’s current value.
Kassy works with homeowners across Florida to review insurance options for luxury homes, waterfront properties, and high-rise condos.
About the Author
Kassy Mendez is a Licensed Independent Insurance Agent with Barefoot Insurance Brokers, bringing years of industry experience in personal lines coverage to Florida homeowners and families. Her areas of expertise include flood insurance, homeowners insurance, high-valued and coastal home insurance, wind-only coverage, personal umbrella policies, and auto insurance throughout Florida. Kassandra Mendez is known for helping her insurance clients navigate complex risk exposures with clarity and confidence. You can reach Kassy Mendez directly at kassy@barefootins.com or call/text 754-233-0637 to discuss your insurance needs.
👣 Go Barefoot All Year Long.
by barefootins | Jul 23, 2026 | Florida Insurance, Personal Insurance
Florida Auto Insurance for Coastal Communities
While Sanibel and Captiva are known for their relaxed island lifestyle, residents still depend on reliable transportation. Whether commuting to Fort Myers or exploring Southwest Florida, drivers need dependable Florida auto insurance coverage.
Barefoot Insurance Brokers helps drivers compare policies from multiple carriers to find competitive coverage.
Auto Insurance Options Available
Residents may obtain:
• Standard Florida auto insurance policies through major A rated carriers like Progressive Insurance, GEICO, National General, an Allstate Company, Traveler’s Insurance, Clearcover, ROOT, Mercury Insurance, Kemper, Bristol West of the Farmers Group of Insurance Companies, The General, and more.
• SR-22 insurance filings
• FR-44 insurance policies
• High-risk auto insurance programs
• Owner and non-owner policies
Why Work with an Independent Broker?
Florida Independent insurance brokers like Barefoot Insurance Brokers can compare multiple insurance carriers at once, helping drivers find competitive pricing and coverage options.
Contact Allie Horblitt
Drivers living on Sanibel Island and Captiva Island can contact Allie Horblitt for a free auto insurance quote.
About the Author
Alexandra “Allie” Horblitt is a Licensed Independent Insurance Agent with Barefoot Insurance Brokers., bringing over 14 years of industry experience to her clients. She specializes in marine artisan insurance, workers’ compensation including USL&H, general liability, and commercial auto coverage. Allie is licensed to sell commercial insurance products in Alabama, Florida, Georgia, Colorado, Indiana, Ohio, Texas and Virginia. To connect with Allie for customized coverage solutions, email her at allie@barefootins.com or call/text 786-440-8242
by barefootins | Jul 20, 2026 | Florida Insurance, Personal Insurance
If you’ve recently been told you need FR44 or FR-44 insurance in Florida, you’re probably asking the same questions we hear every week at Barefoot Insurance Brokers.
“What is FR44?”
“Why do I need it?”
“How can I get my license reinstated?”
The good news is you’re not alone.
What Is FR44 Insurance?
Despite the name, FR44 isn’t actually a type of insurance policy.
An FR44 is a certificate your insurance company files with the Florida Department of Highway Safety and Motor Vehicles (FLHSMV) showing that you carry the required liability insurance after certain DUI-related convictions.
Why Is FR44 Different?
Florida requires much higher liability limits for drivers who must carry an FR44 than for standard auto insurance policies. You typically need a $100,000/$300,000 split limit liability on your auto insurance in Florida to satisfy the FR-44 insurance requirement.
This added financial responsibility is one reason premiums may increase after a DUI conviction.
Can You Switch Insurance Companies?
Yes.
Many Florida drivers believe they’re stuck with their current insurance company after an FR44 requirement.
In many cases, you can compare other insurance options—as long as the required filing remains active without a lapse. You must carry the FR-44 insurance filing for 3 years in total once your license or driving privledge is reinstated.
How Long Will I Need FR44?
Most Florida drivers are required to maintain continuous FR44 coverage for several years.
Allowing your policy to lapse could result in additional penalties or another license suspension.
Barefoot Insurance Brokers Can Help
Every driver’s situation is different.
Whether you’re in Fort Lauderdale, Margate, Coral Springs, Pembroke Pines, Hollywood, Boca Raton, Titusville, Melbourne, Stuart, or anywhere else in Florida, Barefoot Insurance Brokers can help you review available FR44 insurance options and explain the filing process.
If you’ve been told you need FR44 insurance, our team is here to answer your questions and help you get back on the road.
About the Author
Alexandra “Allie” Horblitt is a Licensed Independent Insurance Agent with North Broward Insurance Solutions, Inc., bringing over 14 years of industry experience to her clients. She specializes in marine artisan insurance, workers’ compensation including USL&H, general liability, and commercial auto coverage. Allie is licensed to sell commercial insurance products in Alabama, Florida, Georgia, Colorado, Indiana, Ohio, Texas and Virginia. To connect with Allie for customized coverage solutions, email her at allie@northbrowardinsurance.com or call/text 786-440-8242.
👣 Go Barefoot All Year Long.